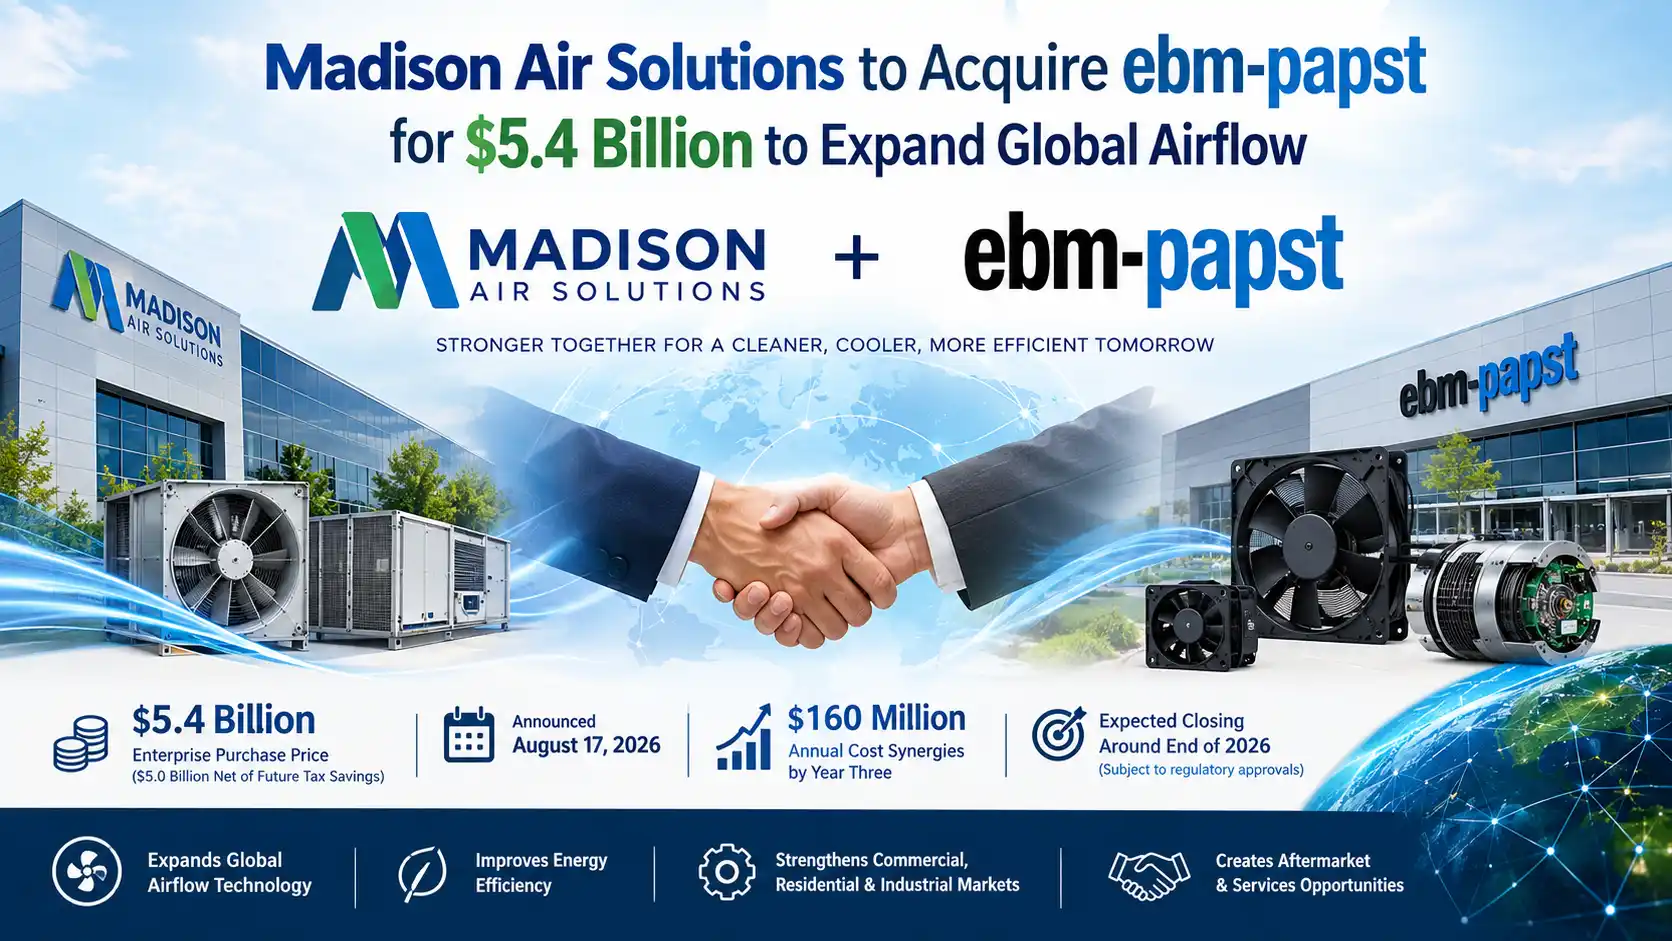
Madison Air Solutions Corporation has entered into a definitive agreement to acquire ebm-papst Group at an enterprise purchase price of $5.4 billion, or $5.0 billion net of future tax savings (effective enterprise purchase price).
The deal, announced on August 17, 2026, is designed to nearly double Madison Air addressable market while vertically integrating differentiated airflow technology and expanding commercial segment, aftermarket and services opportunities.
The acquisition is strategically important because mission-critical air quality, cooling and industrial process applications require integrated electronically commutated (EC) fan and motor systems that improve energy efficiency, enhance reliability and reduce lifecycle costs. Capturing higher-margin electronics pools is becoming increasingly important.
By combining Madison Air application expertise, trusted customer relationships and proven 80/20 operating model with ebm-papst integrated airflow technology and custom engineering expertise, the companies aim to deliver Return on Air capabilities across commercial and residential markets.
The transaction is expected to close around year-end Dec 31, 2026, pending merger control, foreign investment approvals and EU Foreign Subsidies clearance, with €250M break fee in certain seller terminations. $160M annual cost synergies by year three expected.
Key Details of the Acquisition
| Detail | Information |
| Acquirer | Madison Air Solutions Corporation (MAIR) |
| Target | ebm-papst Group |
| Acquirer Country | United States |
| Target Country | Germany |
| Acquirer Industry | Air Quality Solutions, HVAC, Indoor Air Systems |
| Target Industry | High-Performance Airflow Technology, Fans and Motors, EC Systems |
| Deal Type | Acquisition – Locked-Box SPA |
| Deal Value | €4.775 Billion / $5.4 Billion |
| Payment | Cash on hand + debt and equity financing, fully underwritten financing commitments from UniCredit and Wells Fargo, not subject to financing condition |
| Announcement Date | August 17, 2026 |
| Expected Closing | Around Dec 31, 2026 (year-end) |
| Acquirer HQ | Chicago, Illinois |
| Acquirer Stock | NYSE: MAIR |
| Acquirer Leadership | Chairman Founder Larry Gies, President and CEO Jill Wyant |
| Target HQ | Mulfingen, Baden-Württemberg, Germany |
| Legal Advisors | Paul Hastings, Kirkland & Ellis, Hengeler Mueller (Madison), Milbank (owner families), 3-4 firms steered in 10 weeks, €4.78B ($5.6B) |
Madison Air Solutions Company Introduction
Madison Air Solutions Corporation is a U.S.-based global provider of air quality solutions headquartered in Chicago, Illinois, founded 2017, listed NYSE: MAIR with $2.2B IPO terms. Founder Chairman Larry Gies, President and CEO Jill Wyant.
Brands: Addison, AprilAire, Big Ass Fans (best-known ceiling fans, beloved by car dealerships and homeowners, acquired $1.1B 2021), Broan-NuTone, Nortek Air Solutions, Nortek Data Center Cooling, Reznor.
Commercial business serves hospitals, data centers (hyperscale data center cooling angle, AI infrastructure demand), residential business includes AprilAire Healthy Air System.
Booked $3.34B revenue for year ended Dec 31 2025, net income $124.3M, $3.3B LTM Dec 31 2025, 66% commercial 34% residential, 8,650 employees, 13 deals since 2017 representing $8B+ capital, $3.6B Nortek Air Management from Melrose 2021. Mission to make world safer, healthier, more productive through power of better air.
ebm-papst Company Introduction
ebm-papst Group is a Germany-based leading global supplier of high-performance airflow technology, headquartered Mulfingen, Germany, founded 1963 by Gerhard Sturm together with Heinz and Günther Ziehl, sons of Emil Ziehl, to build small fans, started with 35 employees. Parent Elektrobau Mulfingen GmbH & Co. KGaA, Group formed 2003 from merger of Elektrobau Mulfingen GmbH & Co. KG (ebm), Papst Motoren GmbH, Motoren Ventilatoren Landshut GmbH (MVL). CEO Klaus Geißdörfer.
Business: Electric motors and fans, high-performance airflow technology, pioneer in integrated electronically commutated EC fan and motor systems, more than 250M fans installed worldwide within Air Technology business, 1,200+ patents, specified early in HVAC/R design process, helps customers improve energy efficiency, enhance reliability, reduce total lifecycle costs across mission-critical applications.
Revenue 2.408B EUR 2023/24, expected $2.8B revenue and $343M adjusted EBITDA 2026, 13,800 employees 2023/24, ~14,000 globally, ~15,000 globally, 29 production sites worldwide, operating ~40 countries, diversified global customer base. Family-owned by Sturm and Philippiak families.
Why Is Madison Acquiring ebm-papst?
| Madison Already Has | ebm-papst Brings |
| Air quality solutions portfolio (Big Ass Fans, Nortek, AprilAire) | Integrated EC fan and motor technology, 1,200 patents, 250M fans installed |
| Application expertise, trusted customer relationships | High-performance airflow technology, custom engineering expertise |
| Proven 80/20 operating model driving margin expansion | Products specified early in HVAC/R design, mission-critical |
| Commercial segment, aftermarket | 40 countries, $2.8B revenue, $343M EBITDA, broadens commercial, aftermarket, services |
What Does ebm-papst Technology Do?
1. HVAC/R design process needs airflow performance
2. ebm-papst integrated EC fan and motor systems specified early
3. Fans enable airflow performance customers depend on every day
4. Improves energy efficiency, reliability, reduces lifecycle costs
5. Serves mission-critical air quality, cooling, industrial process, healthcare, semiconductor manufacturing
In simple terms: Air Technology Need → EC Fan/Motor System → Energy Efficiency + Reliability → Mission-Critical Uptime → Return on Air
Why Is Vertical Integration Important?
| Non-Integrated Model | Vertically Integrated Model (Madison + ebm-papst) |
| Buy fans/motors from third party | Own EC motor technology, capturing higher-margin electronics pools |
| Limited aftermarket and services | Larger installed base 250M fans, broader customer relationships, expanded channel |
| Lower margin electronics pool missed | Accelerate innovation, holistic solutions throughout full product lifecycle |
| Single market exposure | +$30B addressable market, durability and resilience across cycles |
$5.4 Billion Transaction with Synergies
- Enterprise purchase price $5.4B / €4.775B, effective $5.0B net of future tax savings (€4.412B cash at closing + €371M NPV of amortization over 15 years), 14.6x 2026 forecasted EBITDA, 10x including run-rate synergies
- $160M annual run-rate cost synergies by year three driven by 80/20 operating model, scale, procurement savings, operational efficiencies plus cross-selling, collaborative innovation, deeper customer relationships
- Accretive to adjusted EPS first full year, strong free cash flow, leverage <4.0x at closing target 2.5x trailing 12-month within 2 years
- Nearly doubles addressable market +$30B, broadens aftermarket and services opportunity
- Funding via cash on hand + debt and equity, fully underwritten commitments UniCredit and Wells Fargo, no financing condition
- Closing target Dec 31 2026 pending merger control, foreign investment, EU Foreign Subsidies clearance, €250M break fee in certain seller terminations
- Legal advisors Paul Hastings, Kirkland & Ellis, Hengeler Mueller for Madison, Milbank for owner families, deal negotiated in 10 weeks, €4.78B ($5.6B)
- Madison shares surged 12.1% after $2.25B raised for acquisition, P/E 96.8x well above industry average
Potential Challenges
| Risk Area | Details |
| Regulatory | Merger control, foreign investment, EU Foreign Subsidies clearance, €250M break fee |
| Leverage | Pro forma net leverage <4.0x at closing, plan to deleverage to ~2.5x within 2 years – disciplined path required |
| Integration | Integrating 40-country, 29-site, 13,800-employee family-owned German business into US operating model, HGB vs GAAP differences, purchase price accounting |
| Valuation | 14.6x forecasted 2026 EBITDA, 10x with synergies – relatively high vs industry, P/E 96.8x |
| Market | Economic cycles, demand in commercial and residential markets |
Outcome
Analytical Outcome: This $5.4B / €4.775B deal represents Madison Air largest acquisition to date, paying 14.6x forecasted 2026 EBITDA (10x post-synergy) for ebm-papst $2.8B revenue and $343M EBITDA, a premium justified by vertical integration of mission-critical EC motor technology that captures higher-margin electronics pools and nearly doubles addressable market by $30B. Strategically, Madison pivots from a private rollup of 13 brands ($8B+ capital, $3.34B revenue) into an integrated airflow platform with 1,200 patents and 250M installed fans, broadening aftermarket and services durability while leveraging its proven 80/20 model to deliver $160M synergies by year three. The transaction is financially accretive (low-single-digit adjusted EPS first year) and supported by $2.25B equity raise and fully underwritten debt from UniCredit/Wells Fargo, though pro forma leverage <4x requires disciplined deleveraging to 2.5x within two years. Risks include cross-border integration of a 14,000-person family-owned German industrial group, HGB to GAAP reconciliation, and regulatory hurdles with €250M break fee, but if executed by Dec 31 2026, Madison could strengthen moat in AI-driven data center cooling and healthcare/semiconductor markets where energy efficiency and uptime are critical.
Source: madison news, SEC